
 简体中文
 繁體中文
 English




































































Demand and Applicability Check
确认业务量、票据类型、纳税申报与财务交接,Identify new transactions、Different needs such as adjustments or subsequent maintenance。

了解代理记账服务的适用情形、Data verification、Processing Steps and Common Issues。
52 Daiban:以中小企业国内经营为起点,梳理设立、license、账户与跨境配套的衔接。
深圳代理记账面向需要代理记账服务的企业。Let's first understand the actual business operations or application situation,核对业务量、票据类型、纳税申报与财务交接,Reorganize the handling process and the list of materials。Processing conditions、The requirements and time set by the supervisor shall be subject to the actual matters and the regulations in effect at that time.。
This page focuses on explaining the service content、Preparation and processing steps;The articles below on related topics can be used to further understand specific issues.。If there is already an application or change record,It is recommended to check together with the relevant documents。
Processing Guide:深圳代理记账专题文章
初次沟通先提供业务概况;具体服务工作、企业配合事项与第三方费用需另行确认。
When applying for the first time,First clarify what problem this service solves,Double-check whether it is necessary to arrange the company at the same time、Account、Licensing or financial and tax matters。Prepare materials according to actual use,Avoid investing in supporting procedures in advance if there is no immediate demand.。
When the business or applying entity has not yet been established,Available to viewShenzhen company registrationService scope;The entity registration and the requirements of this business should be checked separately。
按主体类型、税务居住或登记、会计期间及实际收入费用核对申报事项。income tax、流转税、雇主及信息申报各自判断,不以一次报税概括全部义务。
整理银行、支付平台和业务系统数据,核对收入、退款、cost、stock、关联方往来及期初余额。历史差错、遗漏和已收到的通知单列处理,不以直接申报一个零数代替核实。
consultant、Accounting、审计等专业费用与税款、政府收费和可能的逾期费用应分开。历史账务、交易量、资料质量和通知回复会影响工作范围;是否包含更正或补申报需单独确认。
深圳代理记账由深圳市财政局(代理记账机构管理)/税务机关(申报)主管。Is it applicable、Handle according to which category of matters,Depends on the subject qualifications、Business activities and actual location/personnel arrangements;Newly established under the same name、change、continue、Cancellation handled separately,Cannot replace each other。
30 Second key point
Situations that usually require handling:
Easily mistaken as needed、But situations that should be verified separately:
| Material | Key Points / Common Reasons for Returned Items |
|---|---|
| 营业执照与银行开户信息 | |
| 税务登记与票种核定信息 | |
| 原始凭证(发票、bank receipt、合同) | 按月交接 |
| 员工工资表与社保缴纳记录 | |
| 历史账套与申报表(接手时) |
| project | illustrate |
|---|---|
| 建账 | 5–10 个工作日 |
| 月度申报 | 每月 15 日前(节假日顺延) |
| Validity and Renewal | 按年签订服务合同,许可机构需年度备案。 |
| Ongoing obligation | 年度汇算清缴(次年 5 moon 31 日前)、工商年报(6 月 30 日前)。 |
按纳税人类型(小规模/一般纳税人)与票据量计费;Final settlement、审计另计。
| Basis / Entrance | Issuing Authority | Verification method |
|---|---|---|
| "Measures for the Administration of Agency Accounting" | 财政部令第98号 | Enforcement 2019 修订;The current valid text shall prevail |
| 《会计法》 | 全国人大常委会 | Enforcement 2017 修正;The current valid text shall prevail |
| Ministry of Finance | — | Visit |
Date of consultation of the above materials:2026November 12。The provisions of the regulations shall be based on the officially published current text.;Service guidelines have regional differences and version updates,The actual acceptance requirements shall be subject to the standards of the accepting authority at the current period.。
illustrate:This page is a guide for handling conditions and organizing materials,Does not constitute legal advice、Regulatory approval or approval commitment。Submit application、On-site verification、The issuance of certificates and the decision to open accounts are both independently made by the competent authority or the bank.;Specific scope of services、The costs and deliverables shall be subject to written authorization.。
52代办网围绕深圳代理记账的具体事项整理咨询范围,Explain separately the responsibilities of consultants and professional institutions。
确认业务量、票据类型、纳税申报与财务交接,Identify new transactions、Different needs such as adjustments or subsequent maintenance。
梳理账簿、certificate、bill、银行流水及历史申报资料,List missing items and information that needs further confirmation。
Arrange processing nodes after the materials and paths are clarified,And indicate subsequent changes、Maintenance and compliance concerns。
Collect materials according to actual business needs,First, check the applicable items,Confirm the official list again。
The following is for initial communication and plan verification,Formal submission of materials should be according to specific matters、Determined by the current requirements of the jurisdiction and the receiving institution。
Subject agreement:contract、Register、The names and identities in the documents and accounts should correspond with each other.,The relationship between the main entities of the group needs to be explained。
Period and version:Use the currently valid file,Keep the relevant history records at the same time;Do not use expired licenses or old application forms to replace current requirements。
Sending and storage:First provide a business overview,Complete identification document、Bank transactions and customer information are transmitted according to the confirmed scope and channels;Public pages do not display sensitive materials。
The following is the sequence of demand analysis and handling coordination,The specific acceptance procedure shall be verified in accordance with the applicable rules。
沟通主体、业务和目标,确认拟办理的具体事项。
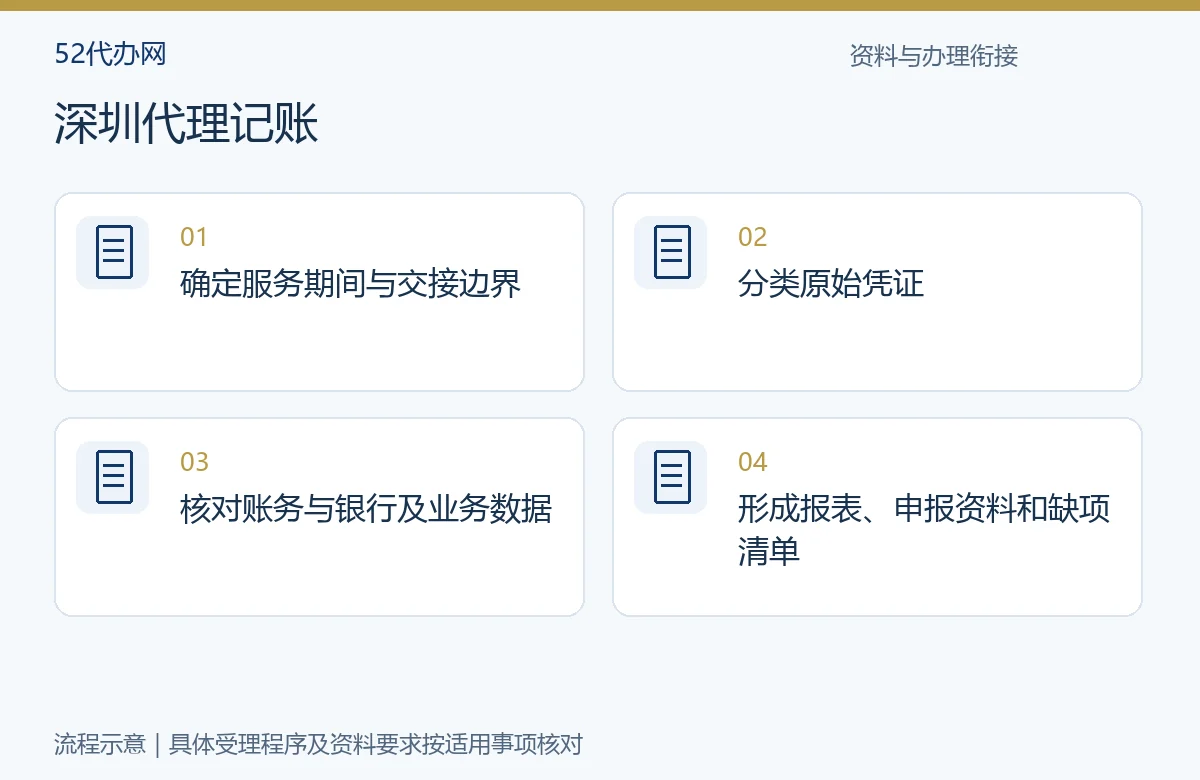
梳理业务量、票据类型、纳税申报与财务交接;识别现有材料与待补项目。
按确定的办理路径整理材料,并跟进提交、补正或沟通事项。
Verify whether the obtained or changed information is consistent with the actual business,Organize follow-up maintenance tasks。
资料交接及申报口径应一致,企业仍需对原始资料负责。This page is for service introduction,Does not replace the current service guidelines issued by the competent authority;The quotation and timeline must be based on the specific business、Confirmed after checking the materials and processing path。
The deliverables of the consulting services should be clearly defined before commissioning.、Data organization and communication scope。If it involves government fees、Translate、Notarization or local professional agency fees,The actual occurrences of the projects should be checked separately、The responsible party and whether it has been included in the quotation;Unconfirmed items are not considered as fixed charge commitments。
Consultant Work Arrangements and Supervisory Authorities、The processing time by the bank or third party should be specified separately.。The progress depends on the completeness of the materials、Correction and external organization arrangements,Specific nodes need to be confirmed after the business scope is clarified.。
记账与税务申报需要企业提供真实交易资料。服务范围应写明申报税种、period、补账和更正是否包含,申报后的凭证仍需妥善保存。
Save the final file、Submit receipt、Matters that need continued cooperation and expiration reminders。Verify the main body in the document、Whether the scope of business or rights aligns with the entrusted objectives;Subsequent changes、declare、Renewal or exit is not included by default in a one-time service。